Turkey’s trajectory since the 1980s has been intertwined with a volatile relationship between its capitalist economy and the persistent feature of high inflation. Examining “Turkish capitalism under inflation” requires peeling back layers: the historical context, the specific economic mechanisms, the visible symptoms, the pervasive impacts across society and industry, and the complex interplay between political choices and market forces that characterize this unique economic environment.
Historical Context: The Genesis of Inflationary Challenges
A brief foray into history reveals that while modern Turkey formally embraced state-led development in the 1950s and 60s, its monetary foundation was precarious. Decades of currency overvaluation, rigid exchange rates aimed at export promotion without adequate competitiveness, significant state spending, and periods of wage and price controls created endemic structural imbalances. The transition from a state-led system towards a more market-oriented model starting in the late 1980s was accompanied by policy shifts that often exacerbated rather than stemmed inflation – expansionary monetary policies, sometimes necessary for financing deficits or stimulating growth, repeatedly clashed with the country’s ability to manage the currency and anchor expectations. This legacy of fiscal dominance over monetary policy, coupled with a gradual erosion of nominal anchors over subsequent decades, cemented high inflation not just as an event, but as the background noise against which Turkey’s market-oriented development has unfolded. The journey thus began not on a solid foundation, but amidst the fundamental tensions between state direction and market-driven, inflation-adjusted capitalism.
Fiscal Foundations: The Engine of Inflation
Understanding Turkish capitalism under inflation requires acknowledging the critical role of fiscal policy. Large, structurally significant deficits in the government budget have consistently required financing, traditionally through the central bank. This “printing press” effect converts fiscal needs directly into broad money supply growth. Historically, external financing through borrowing, particularly before the Convertibility Regime (TKB) of 1994, also contributed significantly. Public expenditure, driven by development goals and administrative needs, stimulates demand throughout the economy and finances large, non-productive segments of the economy. This fiscal impulse, often intertwined with populist pressures and a complex relationship between political imperatives and macroeconomic stability, provides a continuous fuel source for inflation – a dynamic intrinsically linked to how the state spends and finances its role within the market economy. The interplay between these decisions and inflation expectations represents a core paradox.
Symptoms and Metrics: Beyond Simple Numbers
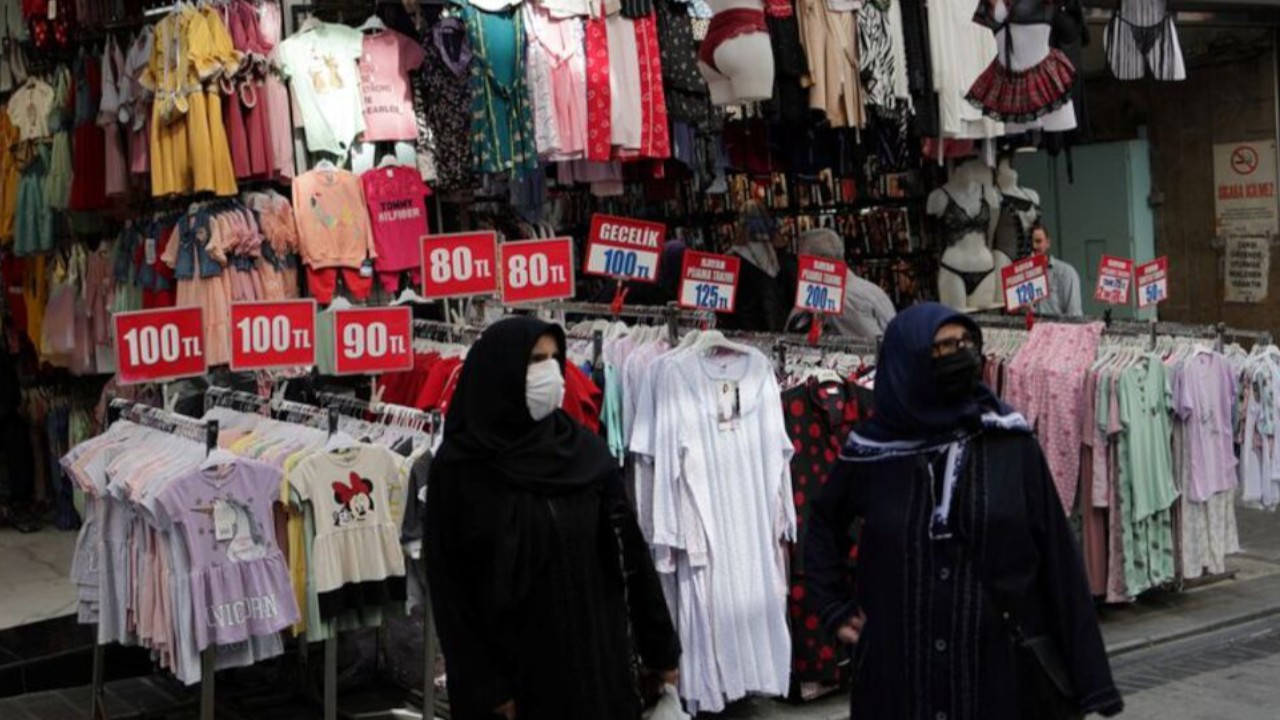
High inflation manifests not merely in headline Consumer Price Index (CPI) figures on government webpages, but in tangible everyday experiences: the rapidly eroding purchasing power of wages, the visible and palpable depreciation of the national currency, the reluctance of citizens to hold cash, and the increased volume of transactions driven by high nominal interest rates. Businesses constantly grapple with Menu Costs – the expense of frequently updating price lists and adjusting menus. The Inflation Tax, disproportionately affecting holders of fixed-denomination assets and savings (though often impacting wage earners more broadly), acts as a hidden national wealth transfer from creditors to debtors. Furthermore, persistent inflation distorts relative prices, making efficiency improvements harder to discern and hindering long-term investment planning. It erodes nominal interest margins for banks and skews intertemporal price signals that guide investment and saving decisions within a capitalist framework. These symptoms underscore the deep incursion of hyper-nominal dynamics into business calculations and personal financial planning.
The Impact: Business Behavior, Investment, and Uncertainty
For businesses operating under conditions of high inflation, decision-making becomes fundamentally different. Investment behaviors are heavily influenced by anticipated, and often high, inflation. The real price of capital goods purchased today, adjusted for future inflation, significantly increases financing and operational costs. Consequently, business cycles often exhibit a perverse relationship – “growth-inflation” is frequently cited, yet underlying productivity gains remain limited, suggesting investment decisions driven more by cash flow and inflation expectations than genuine efficiency improvements. Labor contracts are heavily influenced by inflation clauses, impacting wage trajectory and potentially reducing the real reward for additional effort. The uncertainty surrounding tomorrow’s prices makes long-term planning exceptionally difficult. Firms may focus short-term, invest less, or even engage in export substitution domestically to avoid the complexities and costs of international contracts. High inflation can fundamentally distort capital allocation, resource utilization, and competitiveness – key pillars of market-driven capitalism.
Economic Mechanisms and Policy Nexus
The debate around Turkish capitalism under inflation often centers on the crucial mechanism connecting fiscal policy and monetary policy. The long-standing practice of covering fiscal deficits through central bank financing blurs the lines between government borrowing and base money expansion. This monetary dominance fuels inflation. Central bank independence, often touted as a solution, operates within this fiscal context. As long as large budget gaps exist and fiscal authorities resist inflationary consequences (e.g., by delaying unpopular spending freezes or tax increases), the central bank faces a credibility challenge. Interest rates frequently dominate the policy framework, offering a relatively straightforward (if blunt) tool – nominal rates. Yet, low nominal rates coupled with high expected inflation mean extremely high real rates, which should theoretically discourage borrowing and investment but in practice can sometimes be avoided by borrowers through inflation-indexing arrangements. This interplay between monetary signals, fiscal decisions, and market anticipations forms the bedrock of understanding the persistent inflation phenomenon.
A Glimpse into the Future: Possibility and Reform Imperatives
Addressing inflation requires tackling the structural imbalance at its root. Intergovernmental consensus on adhering to fiscal discipline has been elusive. Yet, market participants constantly weigh political realities against the powerful incentives embedded in high inflation to defer difficult choices. The potential exists for a recalibration – returning to a regime of low, predictable inflation, perhaps anchored by fiscal adjustments, transparent monetary policy, and strong institutions. Such a transition is easier conceived than executed, as the economy has adapted, sometimes inefficiently, to the existing framework of high inflation over decades. The political economy is complex, and entrenched interests exist. For Turkish capitalism to mature beyond the shadow of persistent inflation, it requires acknowledging that inflation is not a mere economic fluctuation to tolerate, but a systemic feature impacting market efficiency, investment patterns, and the legitimacy of the economic model itself. Reform necessitates a fundamental alignment between fiscal management, monetary policy credibility, and long-term development goals.